Editor’s Note: You won’t want to miss the conversation below between Chief Investment Strategist Alexander Green and Oxford Club Pillar One Advisor Conrad Schwalbe, a senior portfolio manager in Florida. (It originally appeared in Liberty Through Wealth earlier this week.)
Conrad recounts the story of how he and his wife sought to build a portfolio to beat inflation… and primarily bought Chief Income Strategist Marc Lichtenfeld’s Oxford Income Letter recommendations!
Conrad also discusses his background as a Marine, his approach to AI, and how investors can increase their “sleep-at-night factor.” It’s a fascinating interview − read the transcript in its entirety below.
– James Ogletree, Senior Managing Editor
Every once in a while, I stop in to get a market take from one of my favorite money managers – the man I recommend each week in my VIP trading services – Conrad Schwalbe, Senior Portfolio Manager for Fund Advisors of America.
Conrad always has an unusual perspective on the market – and usually a strategy that allows him to outperform it soundly.
We sat down at the end of last week to discuss how he is dealing with the recent craziness in the market.
AG: Conrad, your background is quite different from most financial advisors’. Tell readers about your career before becoming a professional money manager.
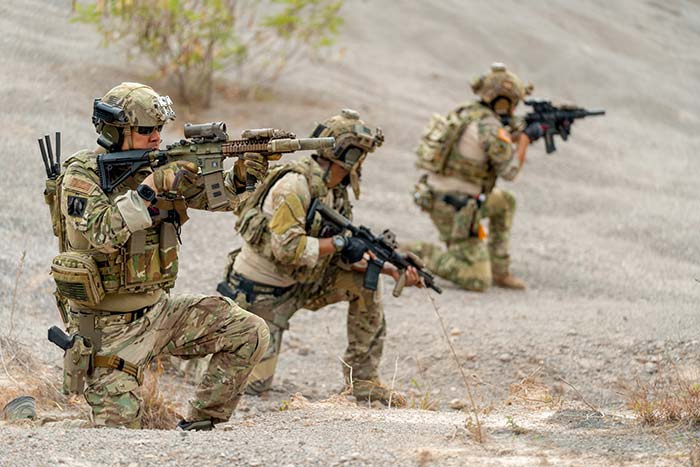
CS: Yeah, my career path has been anything but traditional. I served in the Marine Corps as an assaultman in the infantry before spending more than 15 years working in classified operations for the Defense Department.
I’ve deployed to some pretty risky places, including Iraq and Afghanistan, and spent much of my career in environments where preparation, discipline, attention to detail, and managing risk were not optional.
But, like most folks I suppose, I’ve always been intensely interested in money, and I eventually transitioned into the financial industry. I’m currently a Senior Portfolio Manager with Fund Advisors of America and, of course, a Pillar One Advisor with The Oxford Club.
I’ve found that many of the principles that helped in my previous career translate directly into money management. You have to prepare for scenarios that cannot be known in advance, understand the risks before making decisions, remain disciplined when things get chaotic, and never lose sight of your ultimate objective.
I learned in active combat that you can’t control everything that happens around you, but you can always control how you respond. That strategy works well on the battlefield… and in financial markets too.
AG: What’s your take on the craziness we’ve seen in the markets since the election?
CS: I don’t think the recent volatility was really about the midterms. After all, the polls and prediction markets had been saying for weeks that Democrats were likely to take the House and had a good shot at the Senate.
AG: So what do you think caused all the volatility?
CS: I think it’s a continuation of the tug-of-war between AI bulls, who see huge potential in this transformative technology, and AI skeptics, who see the hundreds of billions in capital expenditures and rightfully wonder when these firms will see a reasonable return on these huge outlays.
AG: So how are you playing it?
CS: With great selectivity. Not all the AI players are going to win, and the sorting process has already begun. The smaller tech companies are already taking it on the chin. Investors wonder whether they have the financial strength to withstand a slowdown in the industry, especially if they have to service a huge debt load. Financial strength is really important right now. That means giants like Amazon and Microsoft should do well long term, regardless of what happens to their share prices in the short term. A lot of smaller companies may not be so lucky.
AG: So what are you doing for your clients to capitalize on opportunities while keeping them safe?
CS: During crazy stretches like this one, they are well protected. We’re not immune to market downturns, but thoughtful portfolio construction helps us weather them better than concentrated holdings in one sector… or even a broadly diversified index fund.
Everyone’s circumstances, goals, risk tolerance, and time horizon are unique. So I listen to what my clients tell me and build portfolios around their specific needs. Ours is not a one-size-fits-all model, which is how many of the largest financial institutions operate.
We’re small enough to develop meaningful relationships with our clients but large enough to provide the kind of sophisticated investment strategies that used to be available only through the big investment banks.
AG: I know that dividend-paying stocks are a cornerstone of your investment approach. That’s worked well this year. Tell me more about that.
CS: Here’s an example from my own life…
A few years ago, my wife and I had the option to pay off our house. Being the numbers nerd in the household, I sat down with her to discuss whether we should pay off the mortgage or invest that money instead.
The decision was actually pretty easy. We had refinanced during COVID and locked in a 2.75% mortgage. The question became: Can I reasonably earn more than 2.75% by investing in quality dividend-paying companies?
The answer, of course, was absolutely.
So I constructed a portfolio that was roughly 70% from your colleague Marc Lichtenfeld’s Oxford Income Letter. The remainder consisted of companies I selected myself.
Since then, that account has appreciated approximately 91%, compared with roughly 77% for the S&P 500 over the same period.
But here’s the thing… It’s primarily invested in what most investors would call boring companies.
In October 2022, for example, the S&P 500 was down approximately 25% from its peak. The Nasdaq was down around 35%. Yet that dividend portfolio’s worst decline was only 13%.
That’s one of the things I like about dividend investing. You’re collecting regular income along the way, regardless of what the market is doing.
Don’t get me wrong. I own technology names in other accounts. I believe in long-term growth, particularly with AI. But this particular account has a specific set of objectives: beat inflation, generate regular income, and easily exceed the cost of my mortgage.
I took enough risks clearing houses in Fallujah a couple of decades ago. Today, I look for stability, income, and peace of mind.
And four years later, the appreciation is substantial enough that I could purchase another house with the gains.
AG: Do you always use Oxford Club investment recommendations when managing client portfolios?
CS: I use quite a few of The Oxford Club’s publications, depending on what a particular client is trying to accomplish.
For those primarily interested in growth, I incorporate recommendations from The Oxford Communiqué, including the Gone Fishin’, Oxford All-Star, and Fortress portfolios. I also use selections from The Insider Alert and The Momentum Alert, along with smaller allocations to Oxford Microcap Trader and some of Dr. Mark Skousen’s recommendations.
For clients focused on income, I lean heavily on Marc’s Income Letter and bond recommendations.
For clients who want a combination of growth and income, I build a portfolio using a blend of these strategies.
But there’s something I consider just as important as which investments we select: position sizing and risk management.
I generally limit any individual recommendation to no more than 4% of a client’s portfolio, at least initially. And for many of the trading recommendations, I also use trailing stops. That gives us a well-defined risk management framework.
AG: You’ve been talking quite a bit about income lately. Tell us about the weekly income strategy you use.
CS: This is probably one of the more interesting developments in our business.
Marc Lichtenfeld and his team have been researching ways to generate income by selling options. Now, when some investors hear the word “options,” they immediately run for the door. But I’m not talking about speculation here.
There’s another side to options that most investors never consider: selling them.
Sellers are essentially providing insurance to buyers in exchange for collecting a premium.
The buyer pays a premium for protection or for the opportunity to profit from a particular price movement. The seller collects that premium and assumes the corresponding risk.
Warren Buffett is one of the most famous examples of someone who has sold options on a massive scale.
In the mid-2000s, Berkshire Hathaway sold long-dated put options tied to major stock market indexes, collecting roughly $4.9 billion in premiums.
Buffett was essentially betting that over a long period of time, the markets would not fall below certain levels.
That’s a bit different from what we’re doing, but the underlying concept is the same: getting paid to take a defined risk.
AG: So how does Marc’s weekly income strategy actually work?
CS: Glad you asked since I’m very familiar with it. Marc and I even gave a joint presentation on the strategy at FreedomFest in Las Vegas earlier this year.
It’s called a put credit spread. And here’s how it works…
Rather than simply selling a put and taking on potentially substantial downside exposure, we simultaneously sell one put and buy another put at a lower strike price. Both options have the same expiration date.
That creates a defined-risk trade with a maximum potential loss that can be calculated before entering the position.
Marc and his team backtested different approaches to determine which underlying investment offered the best opportunity for this strategy. They settled on the Russell 2000, an index of smaller publicly traded companies.
That makes sense. Smaller companies generally experience greater volatility, and greater volatility tends to increase option premiums.
Marc has a live broadcast every Friday morning at 10 a.m. Eastern, where he walks viewers through the trade. I watch each week with coffee in hand.
His backtesting showed a high historical win rate for the strategy. And since its launch, it has also performed very well, although past performance – as the boilerplate reminds us – doesn’t guarantee future results.
As a money manager, however, I have some flexibility that most individual investors don’t.
I’m monitoring the markets all day, every day, and continually refining the strategy.
The results have been pretty exceptional − and encouraging enough that several clients have asked me to incorporate the strategy into their portfolios.
Some prefer Marc’s original approach, some prefer my variation, and others want a combination of the two.
Of course, markets can move sharply, so proper position sizing and disciplined execution are critical.
AG: What would you say to an investor who is concerned about recent volatility but still needs to grow his or her wealth?
CS: I think technology and artificial intelligence have tremendous long-term potential. I own many of the major tech companies, and I believe there will be enormous opportunities over the coming years.
But – let’s be frank – it’s bound to be a bumpy ride. So anything you can do to increase the sleep-at-night factor is going to make it easier to stick with the program over time.
That’s why I like combining select growth investments with dividend-paying companies, fixed income, and income-generating strategies like Marc’s Weekly Income Alert.
There isn’t one perfect investment strategy for everyone. A retiree who needs monthly income has very different needs from a 45-year-old who is still in the wealth accumulation phase.
My job is to understand those differences and build a portfolio accordingly.
Ultimately, investing isn’t about finding one magic stock or chasing the latest hot investment.
It’s about putting together a strategy that makes sense for your circumstances, managing risk, and letting your money work for you.
Your objective in the financial markets is the same as your objective in battle: Survive so that you and your family can enjoy the rest of your lives together. It’s not just about making a killing. It’s also about avoiding getting killed.
AG: Thanks, as always, for your thoughts, Conrad.
Readers with $100,000 or more to invest may want to reach out to Conrad Schwalbe to learn more about his managed accounts or any of these strategies. He also offers Oxford Club Members a complimentary portfolio assessment.
He can be reached at cschwalbe@fundadvisorsofamerica.com.
To learn more about Marc’s Weekly Income Alert, call the Oxford Club VIP Member Services Team at 888.570.9830. If you reach the team outside of normal business hours, your call will be returned the next business day.