Artificial intelligence is creating enormous demand for computing power. But as companies build more complex systems, they also need ways to keep those systems running.
That’s where Datadog (Nasdaq: DDOG) comes in.
Datadog sells software that helps businesses monitor their websites, apps, cloud systems, and AI tools. Its platform lets engineers spot problems, track performance, and identify security threats before they cause major disruptions.
Business is growing fast.
Third quarter revenue jumped 35% to $1.2 billion, while the number of customers spending at least $100,000 a year rose 20% to about 4,860.
More important, that growth is producing cash.
Datadog generated $290 million in operating cash flow during the quarter. After capital spending, it kept $251 million in free cash flow.
However, there’s a wrinkle in the growth story.
Datadog’s largest customer, an AI company, has begun cutting its usage. That could slow revenue growth even as demand from other customers remains strong.
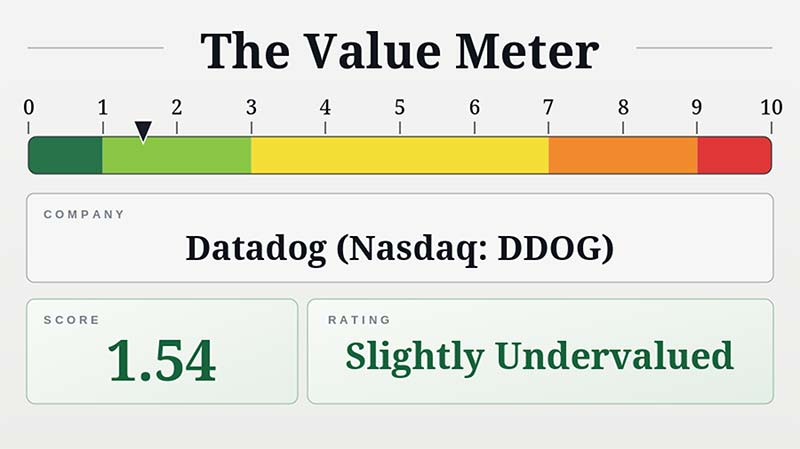
That makes Datadog an interesting test for The Value Meter.
The stock carries an enormous premium to its assets. Yet its ability to generate cash tells a much more compelling story.
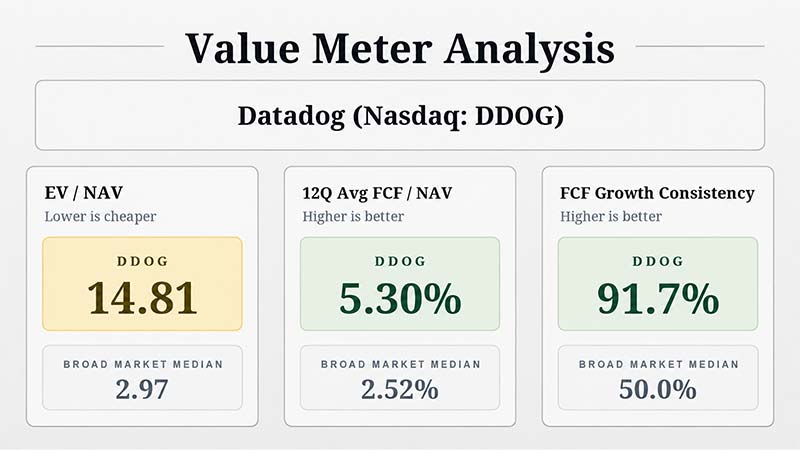
Datadog’s enterprise value-to-net asset value (EV/NAV) ratio stands at 14.81, far above the broad market median of 2.97 and technology sector median of 4.46.
That’s a steep price for the company’s assets, but Datadog’s software business doesn’t require the same physical assets as a manufacturer or utility. Much of its value comes from software and customer relationships that don’t appear on its balance sheet.
Additionally, unlike many expensive growth stocks, Datadog has strong cash numbers to support its valuation.
Its average quarterly free cash flow-to-net asset value (FCF/NAV) percentage over the past three years is 5.30%, more than double the broad market median of 2.52% and well above the technology sector’s 3.60%.
The consistency is even more impressive.
Datadog improved its free cash flow from a year earlier in 11 of the past 12 quarters, giving it a consistency rate of 91.7%. That compares with 50% for the broad market and 58.3% for its sector.
These figures suggest that Datadog is doing more than growing sales. It’s also turning that growth into cash at a steady pace.
Still, investors shouldn’t ignore the valuation premium or the risks tied to the company’s largest customer. If revenue growth slows and cash generation weakens, that premium could become harder to justify.
Datadog’s stock surged above $290 in October, but it has since plunged roughly 40%, giving back much of its gains from earlier this year.
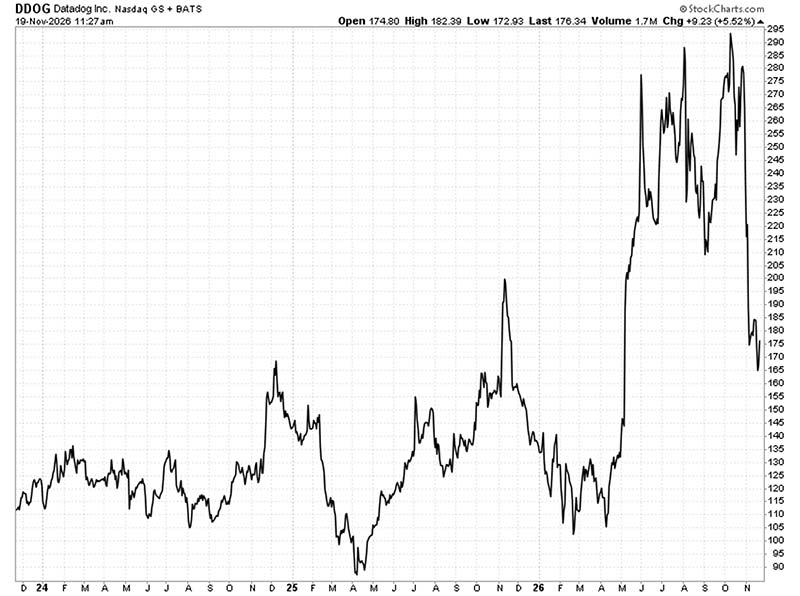
That sharp reversal shows how quickly investors’ expectations can change, even when the underlying business remains strong.
For now, Datadog’s steady cash generation more than offsets its expensive asset valuation in our model.
The Value Meter rates Datadog as “Slightly Undervalued.”
What stock would you like me to run through The Value Meter next? Post the ticker symbol(s) in the comments section below.